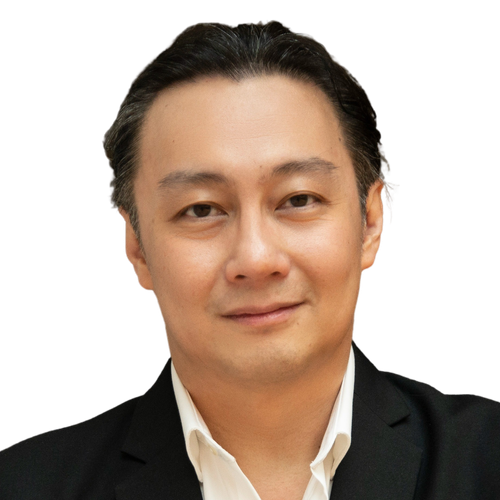


Jesse McWaters
EVP, Head of Global Policy
Mastercard
Jesse McWaters leads Mastercard’s global policy function, where he is responsible for directing the company’s policy strategy on a wide range of issues including digital assets, cross-border payments, real-time payments, open finance, digital ID, cyber-security, and fraud. Prior to joining Mastercard, Jesse served as Financial Technology & Innovation Lead at the World Economic Forum and as a financial services strategy consultant at Deloitte, supporting large-scale technology transformations and the roll-out of new business models for leading banks, insurers, and wealth managers.
Speaking At
-
11:30am–1:00pmTue 17 NovPublic-Private RoundtableRoundtable Room 3Invite-Only
Tokenized Market Infrastructure – The Scaling Challenge
Multi-Issuance and Its Alternatives: Making Cross-Border Stablecoin Recognition Work
-
 Aymeric SalleyHead of Digital Assets PlatformBanking Circle
-
 Chengyi OngDirector of Policy & Regulatory Strategy, APACCircle
-
 Jesse McWatersEVP, Head of Global PolicyMastercard
-
 Jonah CraneHead of Global Regulatory & Policy StrategyStripe
-
 June LauAPAC Head of Policy & Regulatory AffairsElliptic
-
 Lesley ChavkinHead of PolicyRibbit Capital
-
 Peter KerstensAdvisor, DG FISMAEuropean Commission
-
 Rahul AdvaniGlobal Co-Head of PolicyRipple
-
 Sasha MillsExecutive Director of Financial Market InfrastructureBank of England
-
 Jannah PatchayExecutive in Residence & Board MemberGlobal Digital FinanceModerator
About this session
The GDF Global Stablecoin Regulatory Playbook, published in January 2026, set out shared terminology and outcome-based principles for stablecoin regulation across jurisdictions. The subsequent report ‘Global Stablecoin Regulatory Frameworks: Closing the Gap’ drawn from insights at the Point Zero Forum in June 2026 took this work a step further. It mapped where regulators already agree and isolated the one problem that domestic frameworks were never designed to solve: how a stablecoin issued under one jurisdiction's rules can circulate safely under another's.
The report framed two models for scaling beyond domestic rules. The first keeps issuance local while seeking to preserve a unified token, through multiple licensed entities issuing a fungible stablecoin under comparable standards. The second permits a foreign-issued stablecoin to operate through recognition based on comparable, rather than identical, regulatory outcomes. It also recorded differing regulatory perspectives on the perceived risk associated with multi-issuance, particularly correlated redemption pressure and the resilience of a stablecoin’s fungibility under stress.
The roundtable convenes policymakers, global standard-setters and industry leaders to examine how these models could operate in practice. When is multi-issuance necessary to meet host-jurisdiction objectives? When can unilateral or mutual recognition provide sufficient safeguards? Where a combination of the two is appropriate, how should responsibility for reserves, redemption, supervision and crisis management be allocated? The session will focus on the conditions needed to make each approach workable while preserving fungibility and avoiding unnecessary regulatory fragmentation.
-
-
3:00–4:30pmTue 17 NovPublic-Private RoundtableRoundtable Room 4Invite-Only
Tokenized Market Infrastructure – The Scaling Challenge
Enterprise Tokenized Settlement: Can Convertibility Hold Under Stress At Scale?
-
 Avalon IngramDigital Assets Business LeadSwift
-
Aymeric SalleyHead of Digital Assets PlatformBanking Circle
-
Jesse McWatersEVP, Head of Global PolicyMastercard
-
 John O'NeillManaging Director, Digital Assets & Currencies, CIBHSBC
-
 Dr. Marius SkuodisBoard MemberBank of Lithuania
-
 Sunayna TutejaFormer Chief Innovation OfficerFederal Reserve SystemModerator
About this session
Tokenized money is going plural — stablecoins and tokenized bank deposits are both moving toward live enterprise use in 2026, but they hold their value at par through different mechanisms, and each faces a different test under stress. Stablecoins hold par through reserves and redemption, now being formalized by 2026 rulemaking, from the GENIUS Act to MiCA; under stress, the question is whether reserves and redemption queues hold up in a run. Tokenized deposits hold par through the existing two-tier banking system and a central bank's guarantee of convertibility, but scale through interbank plumbing that's still being decided — settlement-bank arrangements or shared platforms. Under stress, the question there is whether that plumbing, and the counterparty exposure it creates, holds up if a bank or a platform fails.
As regulators and participants warned at the Point Zero Forum, the open question is whether convertibility at par survives a crisis in practice, on any of these rails. This session asks what needs to be built at each stage — reserve or capital backing, custody or bank participation, secondary-market trading, and cross-ledger settlement — for that convertibility to hold under stress. It puts reserve-backed and deposit-backed models on equal footing: where each is already resilient, where each is still exposed, and whether a fragmented rails landscape is itself becoming the bigger risk to singleness than any one model's design.
-