

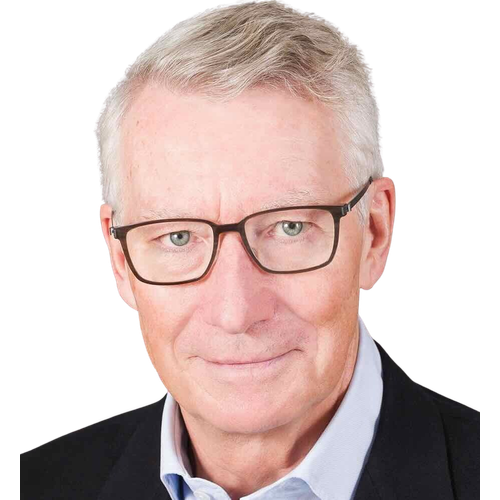
Prof. Bob Wardrop
Founder & Chief Executive Officer of RegGenome
Cambridge University & RegGenome
Robert (Bob) Wardrop is Founder and CEO of RegGenome, a regulatory data infrastructure company. RegGenome turns complex global regulation into structured data that retains the meaning and context of each requirement and stays traceable to its original source, supporting policy, supervision, risk and compliance.
Bob was Management Practice Professor of Finance at Cambridge Judge Business School, and founding Director of the Cambridge Centre for Alternative Finance until 2020. His research studied innovation at the intersection of technological change and the global financial system, and in 2021 he received the CJBS Research Impact Award for his work applying AI to regulatory information in the field of computational regulation.
That research led to the founding of RegGenome, which has its origins at the University of Cambridge and is a founding member of the Regulatory Genome Project, an ongoing public-private initiative standardising how regulation is structured. RegGenome data and models are used by 100 regulatory organisations, and by three of the world's 29 globally systemically important banks.
Bob has held several advisory board roles with regulatory authorities and corporate directorships over the course of his professional career. He holds an MBA from the Booth School of Business at the University of Chicago, an MSc from the London School of Economics, and a PhD from the University of Cambridge.
Speaking At
-
12:00–1:00pmTue 17 NovWorkshopWorkshop Room 2OpenModerator
Others
Human and Machine: Building the Next Generation Regulatory Inventory for Trusted Agentic AI - Powered by RegGenome
-
 Christine EngstromDirector GeneralAsian Development Bank
-
 Shayan HazirChief Digital Officer, Asia (xHK) & MENATHSBC
-
 Prof. Bob WardropFounder & Chief Executive Officer of RegGenomeCambridge University & RegGenomeModerator
About this session
How can AI agents interpret regulation reliably when people already struggle to keep pace with its volume and complexity? Trusted agentic AI requires authoritative regulatory information organised so that people and machines can understand and use it consistently.
This is fundamentally a human-and-machine model. Machines can analyse regulation systematically and at scale, connecting findings to evidence. People contribute legal and institutional context, exercise judgment and remain accountable for consequential decisions. Neither should function in isolation: uncertainty and disagreement must be visible and escalated for human review.
This workshop will explore the regulatory data foundations needed to support this partnership. Participants will consider how shared ways of classifying rules and defining regulatory concepts could enable agents to retrieve the correct provisions, validate interpretations and cite authoritative sources—while reducing duplication for public authorities and global banks.
The discussion will examine different approaches to organising and governing regulatory information, including whether shared standards can enable interoperable systems without requiring a single global classification framework or central database. It will also consider how to preserve jurisdictional authority and institutional control.
Participants will gain a clearer understanding of how to combine machine scale and consistency with human context, judgment and accountability.
-
-
1:30–3:00pmTue 17 NovPublic-Private RoundtableRoundtable Room 2Open
The Scaling Challenge in Tokenized MarketsGlobal Frameworks and Shared Best Practices in Payments Chains
Programmable Compliance: Which Rules Travel with the Money, and How?
-
Prof. Bob WardropFounder & Chief Executive Officer of RegGenomeCambridge University & RegGenome
-
 Ceridwen ChooChief Executive OfficerCleanverse International Pte Ltd
-
 Lindsey ArgalasChief Executive OfficerTaxbit
-
 Matthias ObrechtHead Supervision New TechnologiesSwiss Financial Market Supervisory Authority (FINMA)
-
 Nischint SanghaviHead of Digital Currencies, APVisa
-
 Nora AlbakrDeputy Governor for Financial InnovationSaudi Central Bank
-
 Sonja DavidovicSenior Digital Expert on Transformative TechnologyInternational Monetary Fund
-
 Varlam EbanoidzeHead of FinTech Development & Innovation OfficeNational Bank of Georgia
-
 Vinay PalathinkalGeneral Manager, APACLorum
-
 Audrey MetzgerDirector of Innovation & Financial Market InfrastructuresBanque de France
-
 Nilixa DevlukiaChairOpen Finance AssociationModerator
About this session
As money becomes programmable, across central bank digital currencies, tokenized deposits, and stablecoins, a real question is emerging about where compliance should live: embedded directly in the asset as a rule that travels with it, layered on top through richer messaging and real-time screening, or enforced separately by whichever party touches the transaction last.
Players are all building credible but different answers in parallel, and none has converged on how these should interoperate across jurisdictions with different compliance regimes. The stakes are rising on every front — real-time cross-border settlement, tokenized securities, and increasingly, autonomous agents initiating transactions on their own — all of which need a compliance check at the moment value moves, not after. What would each of these approaches to programmable compliance actually need to interoperate, and which rules win when they conflict across borders?
Discussion questions:
1\. Should compliance logic live in the asset itself, in the messaging/settlement layer, or in a separate real-time screening service, and does the answer change depending on whether it's a CBDC, a tokenized deposit, or a stablecoin?
2\. When a transaction crosses borders, whose compliance rule actually governs — sender's jurisdiction, receiver's, or the rail's — and what happens when they conflict?
3\. Retrofitting compliance onto existing settlement infrastructure and building it in from scratch are both live strategies right now — what would each need to prove to become the default, and is convergence between them actually possible?
4\. As more transactions — including those initiated by autonomous agents — require a compliance check the moment value moves, what are the minimum interoperability standards needed for rules to actually travel with money across rails?
-

